Buying a Home in Temecula When Interest Rates Are High
How to afford a Home in Temecula When Interest Rates Are High
Quick answer: High rates make monthly payments larger, but buyers still have real ways to bring them down: shopping multiple lenders, negotiating seller-paid rate buydowns, choosing the right loan type, and lowering the cost of owning the home itself. The best strategy is to focus on the total monthly cost, not just the price or the rate.
I'm Alisa Morrison, a REALTOR® with 17 years of experience helping buyers in Temecula, San Diego, and North County. I'm not a lender, so talk to a licensed loan officer about your own numbers. Here is what I walk buyers through.
1. See what one percentage point actually costs
On a $750,000 home with 20 percent down, the loan is $600,000. At 7 percent, the principal and interest payment is roughly $3,990 a month. At 6 percent, it is roughly $3,600. That is about $390 a month, or more than $4,600 a year, for a single percentage point. That gap is why rate negotiation is worth your time.
Principal and interest only. Property taxes, insurance, HOA dues, and Mello-Roos are extra.
2. Shop at least three lenders
Rates and fees vary by lender, even on the same day for the same borrower. Get written Loan Estimates from at least three, including a bank, a credit union, and a mortgage broker, and compare the rate, the points, and the closing costs together.
3. Ask the seller to help with a buydown
In a balanced market like Temecula's, many sellers will pay closing costs or fund a rate buydown. A temporary buydown (such as 2-1) lowers your rate for the first one or two years. A permanent buydown (buying points) lowers it for the life of the loan. Ask your agent to structure the offer so the concession is built into the price negotiation.
4. Compare loan types, not just rates
- Conventional: Good for strong credit and larger down payments.
- FHA: Lower down payment and credit requirements. It includes mortgage insurance.
- VA: For eligible veterans and service members, often with no down payment.
- Jumbo: For higher loan amounts. Check the current conforming loan limit, because it affects pricing in higher-priced areas.
- Adjustable-rate (ARM): A lower starting rate with the risk of adjustment later. This only makes sense if you understand the caps and your plan to sell or refinance.
5. Look at assumable loans
Some FHA and VA loans can be taken over by a buyer at the seller's original rate. If a seller has a low-rate assumable loan, the savings can be significant, though you will need cash or a second loan to cover the gap between the price and the remaining balance. Ask your agent to flag these listings.
6. Check down payment assistance
California and local programs change, and funding can run out. Ask a lender about current first-time buyer and down payment assistance programs before you assume you don't qualify.
7. Consider an energy-efficient mortgage
Programs such as the FHA Energy Efficient Mortgage and some conventional "green" loan options can finance efficiency upgrades along with the purchase. Not every lender offers them, so ask early.
8. Reduce the cost of ownership, not just the loan
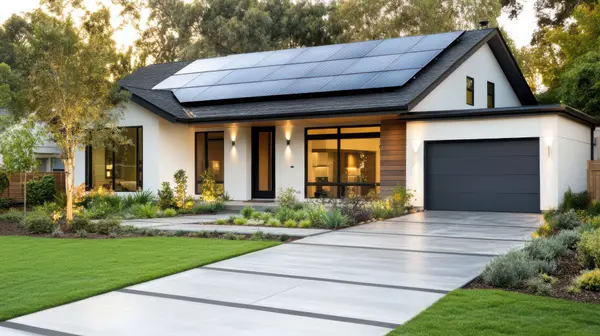
This is where my specialty comes in. Two homes at the same price can have very different monthly costs. A home with efficient HVAC, good insulation, quality windows, and owned solar can cut hundreds of dollars a month from electric bills, which can matter as much as a lower rate. I work with Pearl Certification to document a home's performance, so you can compare real operating costs, not guesses. That is what Making Value Visible means for a buyer.
9. Don't count on refinancing
Many buyers plan to refinance if rates fall. That may work out, but nobody can promise it. Choose a payment you can carry at today's rate, and treat a future refinance as a bonus.
Frequently asked questions
How much house can I afford in Temecula with high interest rates?
It depends on your income, debts, down payment, and rate. Lenders look at your debt-to-income ratio, and you should also budget for taxes, insurance, HOA dues, and Mello-Roos.
What is a rate buydown?
A payment, often from the seller or builder, that lowers your interest rate for the first years of the loan or for its full term.
Is it better to wait for rates to drop?
Nobody can predict rates reliably. Waiting also carries the risk that prices rise or competition returns. Compare the cost of buying now with the option to refinance later against the cost of waiting.
Are there energy-efficient mortgage options?
Yes. Some FHA and conventional programs allow financing of efficiency improvements. Ask a loan officer which ones they offer.
Ready to run the numbers on a Temecula home? Contact Alisa Morrison for a buyer strategy that looks at your payment, your rate options, and the true cost of owning each home. Call or text 951-491-5838, email AlisaAMorrison@gmail.com, or visit www.alisamorrison.com.
Alisa Morrison, REALTOR® | DRE #01860119 | LPT Realty | GREEN · GPRO · SFR · C2EX | Making Value Visible
This is general information, not financial or lending advice. Consult a licensed loan officer and tax professional for your situation.
Categories
Recent Posts
GET MORE INFORMATION